
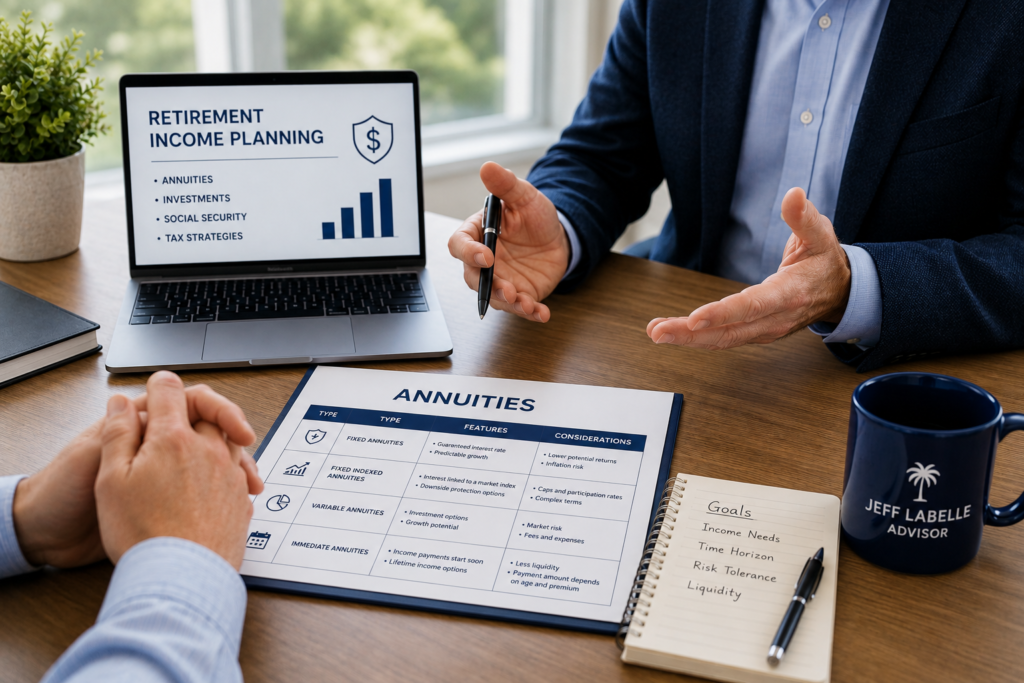
How Annuity Income Can Work in Retirement Planning?
One of the biggest changes that comes with retirement is moving from earning a regular paycheck to creating income from the assets you have accumulated over time.
That transition can lead to an important question: How can retirement assets be converted into a dependable source of income?
Annuities are one financial product that may be considered when evaluating retirement income strategies. Certain annuity contracts can provide income according to contractual terms, including options designed to continue payments for a specified period or for the lifetime of an individual.
For Sarasota residents exploring retirement income options, understanding how annuity income works can help provide a clearer starting point for a financial planning conversation.
What Does an Annuity Income Stream Mean?
When an annuity is structured for income, the contract can provide payments according to its terms.
The amount and duration of those payments can depend on several factors, including the type of annuity, the amount contributed, the age of the annuitant, the selected income option, and the provisions of the contract.
Some contracts may offer income for a specified number of years, while others may provide lifetime income options.
The details matter because different income choices can affect both the payment amount and what happens to the remaining contract value.
Lifetime Income vs. Fixed-Term Income
One feature that can make annuities particularly relevant to retirement planning is the ability of certain contracts to provide lifetime income.
A lifetime income option is designed to continue payments for the life of the person covered by the contract, subject to its terms.
Other options may provide payments for a predetermined period.
Choosing between different income structures involves considering several factors, including expected retirement expenses, other sources of income, liquidity needs, and personal preferences.
What Happens to an Annuity After Income Begins?
This depends on the contract and the income option selected.
Some annuity structures may provide payments for life without returning the remaining contract value to beneficiaries after the covered individual’s death. Other contracts or benefit options may include provisions for beneficiaries.
This is one reason it is important to understand the available options before selecting an income strategy.
A higher or lower income payment may be associated with different contractual provisions, so the decision involves more than simply comparing payment amounts.
Annuity Income and Other Retirement Income
Annuity income does not necessarily have to replace other sources of retirement income.
Many retirees may have several sources of income, such as Social Security, pensions, retirement accounts, investments, rental income, or other assets.
The potential role of an annuity can be evaluated alongside those resources.
For example, someone may want to understand how recurring expenses could be addressed by predictable income sources while keeping other assets available for different purposes.
The appropriate strategy depends on the individual’s circumstances.
The Importance of Liquidity
Creating retirement income is only one part of the equation.
Access to money can also be important during retirement.
Unexpected expenses, home improvements, travel, family needs, or other financial priorities may require access to assets. Annuity contracts can have surrender periods, withdrawal provisions, and other limitations, so liquidity should be considered before entering into a contract.
A retirement income strategy should account for both ongoing income needs and potential future expenses.
Annuity Income Is Based on Contract Terms
It is important to distinguish between general discussions about annuities and the specific provisions of an individual contract.
Income calculations, guarantees, withdrawal provisions, fees, riders, beneficiary provisions, and other features vary by product.
The issuing insurance company’s financial strength is also relevant when evaluating contractual guarantees.
Reading and understanding the actual contract is therefore an important part of the decision-making process.
A Sarasota Perspective on Retirement Income Planning
For individuals in Sarasota approaching retirement, creating an income strategy can involve many moving pieces.
Jeff LaBelle, a Sarasota financial advisor, works with individuals who are evaluating retirement planning and financial strategies, including questions about annuity income.
A conversation can focus on the bigger picture: retirement objectives, anticipated expenses, existing income sources, liquidity needs, and how different financial tools may fit together.
The goal is to understand the individual’s circumstances before determining whether a particular strategy warrants consideration.
Planning Income Before Retirement Arrives
Retirement income planning is often easier when it begins before retirement.
Understanding where income may come from, which expenses need to be covered, and how different assets may be used can help identify questions well before a retirement date arrives.
For Sarasota individuals researching annuities or considering different approaches to retirement income, learning how lifetime and fixed-term income options work can be a useful part of that preparation.
Annuities are not appropriate for every investor, but understanding their income features can help individuals have more informed conversations about their retirement planning options.
This article is for general educational purposes only and is not intended to provide individualized investment, tax, or legal advice. Annuities are insurance products subject to contract terms, fees, expenses, surrender provisions, and other limitations. Guarantees are backed by the claims-paying ability of the issuing insurance company. Income options and benefits vary by contract. Individuals should review applicable contracts and disclosures and consult qualified professionals regarding their individual circumstances.